Mortgage rates have climbed back over 7% this fall. Freddie Mac's weekly average for a 30-year fixed hit 7.40% in mid-October. A year ago it was in the low 6s. On a typical loan, that gap is a couple hundred dollars more every month.
Builders have noticed. The National Association of Home Builders reported this week that 43% of builders cut prices in October, the highest share in its 2020 to 2026 records. About two out of three are using some kind of sales incentive.
The incentive you'll run into most right now is the rate buydown. It's also the easiest one to misread. So here's the plain version, plus what to look for when you compare offers.
What a buydown is
A buydown is money paid up front to lower your mortgage payment. When a builder pays for it, that money goes into an account at closing. Each month the account covers part of your payment and you cover the rest. Your loan still pays down on its normal schedule.
There are two kinds. A permanent buydown uses discount points to lower your rate for the life of the loan. It's steady, but it takes a lot of money to move the rate a little.
A temporary buydown lowers your rate for the first few years, then steps up to your regular fixed rate. A 2-1 covers two years. A 3-2-1 covers three. The biggest break comes in year one, a smaller one in year two, and a smaller one again in year three. From year four on, you pay your normal rate for the rest of the loan.
Why a buydown can beat a price cut
Say a builder has a set amount to put toward a sale. They can take it off the price, or they can use it to buy down your rate.
Off the price, it lowers your loan a little, and that savings gets spread across 360 payments. You'll feel it, but barely. Put toward a buydown, a similar amount goes straight at your payment in the first three years. That's usually when money is tightest anyway. Closing costs, the move, window coverings, a few things for the yard.
A price cut isn't nothing. It lowers your loan balance and your tax basis for good, so it's worth running both numbers with your lender. But for a lot of buyers, the early breathing room is the more useful of the two.
One more thing. If rates come down during those three years, you may be able to refinance. Nobody can promise that, so plan as if you'll pay the full rate from year four on. If rates drop, treat it as a bonus.
What other builders are offering
Buydowns are everywhere right now, from the big national builders to the ones here in Southern Utah. St. George builders are advertising buydowns and lender credits on finished homes, and Cedar City has the same thing going on homes that are already built.
From a distance the offers all look alike. Up close, they aren't.
A lot of the national builders tie their buydown to their own mortgage company, so you only get the advertised rate if you finance with them. Some ask you to pay discount points on top of the buydown. Some advertise a very low first-year rate that sits on an adjustable-rate loan, which means the rate after the buydown isn't locked for 30 years. And some make you pick: put the incentive toward closing costs or toward the buydown, not both.
None of that is wrong. It's just worth reading slowly.
The buydown at Temple View Commons
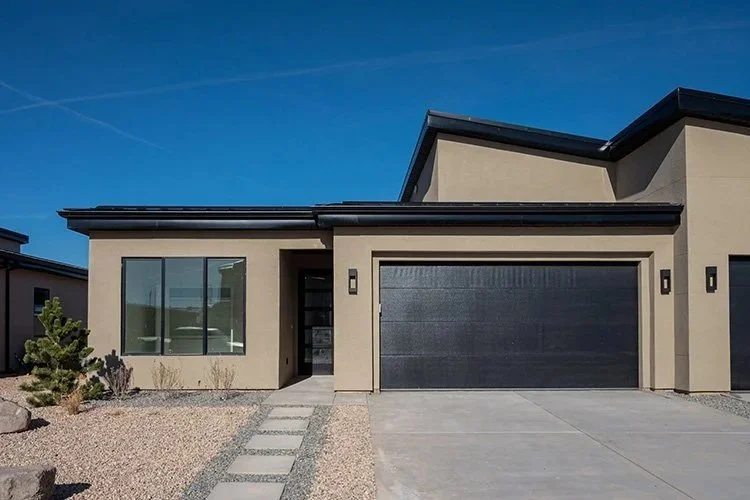
Through November 30, we're paying for a 3-2-1 temporary buydown on two finished Mesa homes, No. 2992 and No. 3008.
Both are single story, 1,490 square feet, with three bedrooms and a bathroom for every one of them. There's a fireplace, 11-foot ceilings in the great room, walk-in closets, a pantry, a standing seam metal roof, and a big backyard. They're done. No build schedule to wait on.
The loan behind the offer is a 30-year fixed, so once the three years are up, your rate stays put. And because we build and sell these homes ourselves, you're talking straight to the people who set the offer. Every buyer also gets access to a real estate attorney to look over the purchase contract.
The full breakdown and terms are on our offer page. Better yet, come walk through them. The model home is open Tuesday through Saturday, 10 to 6. Call or text Jarrod Grannum at 435-383-4040 and he'll show you how the buydown works with your loan.
Offer applies to No. 2992 and No. 3008 only and ends November 30, 2026. Not all buyers will qualify. Mortgage loans are subject to credit approval. Terms subject to change. Equal Housing Opportunity.